

ISCC PLUS is a voluntary, international certification scheme that attests to the origin and traceability of circular materials, such as the oil obtained from plastic waste pyrolysis. With a valid certificate, that output can be sold as certified circular feedstock under mass balance, which opens up demanding markets and makes it possible to capture a premium over the fossil equivalent. The rest of the environmental value depends on the product’s final destination, and not all the “credits” advertised on the market apply to plastic pyrolysis.
What ISCC PLUS is and why it matters in pyrolysis
ISCC (International Sustainability and Carbon Certification) runs several schemes. ISCC PLUS is the voluntary one: it verifies sustainability characteristics of alternative raw materials beyond what the law requires. It is used in plastics and packaging, chemicals, textiles, food and also fuels.
The scheme distinguishes several types of material. For plastic pyrolysis the relevant one is circular material: material that comes from the mechanical or chemical recycling of waste of fossil origin, such as mixed plastics or end-of-life tyres. Alongside it there are bio-circular materials (waste of biological origin), bio materials (cultivated biomass) and materials derived from renewable energy.
In practice, certification answers the question every industrial buyer asks: how do I prove this oil really comes from plastic waste and not from crude? Without that proof, pyrolysis oil competes only on price with a conventional hydrocarbon. With it, it becomes a feedstock with a verifiable circular attribute. The physical process is explained in detail in what plastic waste pyrolysis is.
How mass balance works
When pyrolysis oil enters a refinery or a petrochemical steam cracker, it is mixed with fossil streams. From that point on it is impossible to tell which molecule comes from waste and which from oil. Mass balance solves that problem with audited accounting, not physical separation.
The logic is similar to that of renewable electricity: what enters the system as circular can be allocated, in the same quantity, to output products sold as circular, even if they are not physically the same molecules. For this to be credible, ISCC requires:
- Recording all inputs and outputs of material, sustainable and non-sustainable, over defined balance periods.
- Not selling more as circular than has entered as circular, applying the process conversion factors.
- Issuing a sustainability declaration for every delivery of ISCC PLUS material.
- Having a certificate at every link that handles the material, from the point of origin of the waste to the final brand.
ISCC PLUS allows three chain-of-custody options: physical segregation, controlled blending and mass balance. In chemical recycling mass balance is the most common, because integration into existing facilities is precisely what allows scaling up.
Steps to certify a pyrolysis plant under ISCC PLUS
The process is standardised and is carried out by an independent certification body recognised by ISCC. Broadly speaking:
- Registration. The company signs up as a system user on the ISCC platform and registers its operational unit.
- Choosing the certification body. A quote is requested, a contract is signed and the scope is agreed: which sites, which inputs and which products.
- Documentation. Traceability procedures, a register of waste suppliers with their self-declarations, a mass balance system, conversion factors and management of sustainability declarations.
- Audit. Document review and site visit. If non-conformities arise, corrective actions must be submitted on time.
- Certificate issue. After the technical review, the certificate is published and the plant can start issuing sustainability declarations.
- Annual renewal. ISCC PLUS certificates are issued per site and are valid for 12 months, so the audit is repeated every year.
A practical detail: self-declarations from collection points can cover one delivery or, at most, one year, and must be kept for possible checks. That is why it pays to design waste traceability from the engineering phase, not afterwards.
What environmental value can actually be monetised
Very different instruments are lumped together under the label “environmental credits”. Not all of them apply to plastic pyrolysis, and the deciding factor is what the oil is used for: chemical feedstock or fuel.
If the oil goes to chemical feedstock or new plastic
This is the scenario where ISCC PLUS adds most. The certified circular product is sold at a premium to petrochemical companies and converters that need circular content for their customers and their reporting.
In addition, Regulation (EU) 2025/40 on packaging and packaging waste (PPWR) sets minimum post-consumer recycled plastic content from 2030; for example, 30 % in contact-sensitive PET packaging and 10 % in contact-sensitive packaging made of other plastics. The regulation allows chemical recycling to be counted through mass balance, with calculation rules to be specified in a Commission implementing act. Outputs used as fuel are excluded from that attribution.
In Spain, the special tax on non-reusable plastic packaging is levied at 0.45 €/kg on non-recycled plastic. Spain’s Directorate General for Taxation (DGT) confirmed in its binding ruling V0931-25 (May 2025) that chemically recycled plastic is not part of the tax base if its recycled content is proven. That tax saving belongs to the buyer, but it increases their willingness to pay for certified material.
If the oil goes to fuel
Here the reference tool is not ISCC PLUS but ISCC EU, the scheme that verifies compliance with the Renewable Energy Directive. Fuels obtained from non-recyclable fossil waste are called recycled carbon fuels. The directive allows Member States to take them into account in their renewable transport targets, and Delegated Regulation (EU) 2023/1185 requires them to cut greenhouse gas emissions by at least 70 %. Their value therefore depends on how each country has transposed the directive and on the project clearing that threshold.
What is best ruled out
- Voluntary plastic credits. Verra’s recycling methodology accepts chemical recycling, but expressly excludes projects whose product is used as fuel or for energy recovery.
- Selling “carbon credits” for avoided landfill. This revenue should not be counted on in a business plan without a specific methodology and a registry to back it.
| Output destination | Applicable scheme | Where the value comes from |
|---|---|---|
| Chemical feedstock or polymer | ISCC PLUS (mass balance) | Premium for circular material, PPWR recycled content, buyer’s plastic tax saving |
| Transport fuel | ISCC EU (RED framework) | Recycled carbon fuel, if the Member State counts it and the 70 % saving is met |
| Any destination | Certified traceability | Verifiable ESG reporting and access to buyers who require a certificate |
The other pyrolysis products, gas and char, have their own uses and value logic; we go over them in oil, gas and char: what pyrolysis generates.
How certification turns into revenue
Certification does not generate money on its own. It does so when it is built into the commercial chain. The steps that make the difference are:
- Design traceability around the incoming waste. Know which waste manager each batch comes from and with what documentation.
- Secure the buyer before producing. A long-term offtake agreement that recognises the certified attribute provides a stable price and makes financing easier, as detailed in how a pyrolysis plant is financed.
- Choose the scheme by destination. Do not certify “just in case”, but according to where the product will end up.
- Use the data in reporting. Tonnes diverted from landfill and turned into traced feedstock are a solid metric for sustainability reports and for meeting the zero landfill by 2035 horizon.
How Nantek solves it
Nantek includes the management of environmental credit certifications within its end-to-end model, together with turnkey EPC, structured financing, operation and maintenance and offtake. The monetisable value is shared: Nantek passes on to the client part of the net profit generated by those certifications.
- Certifications held: ISCC, ISCC PLUS and CGN, plus ECHA registration.
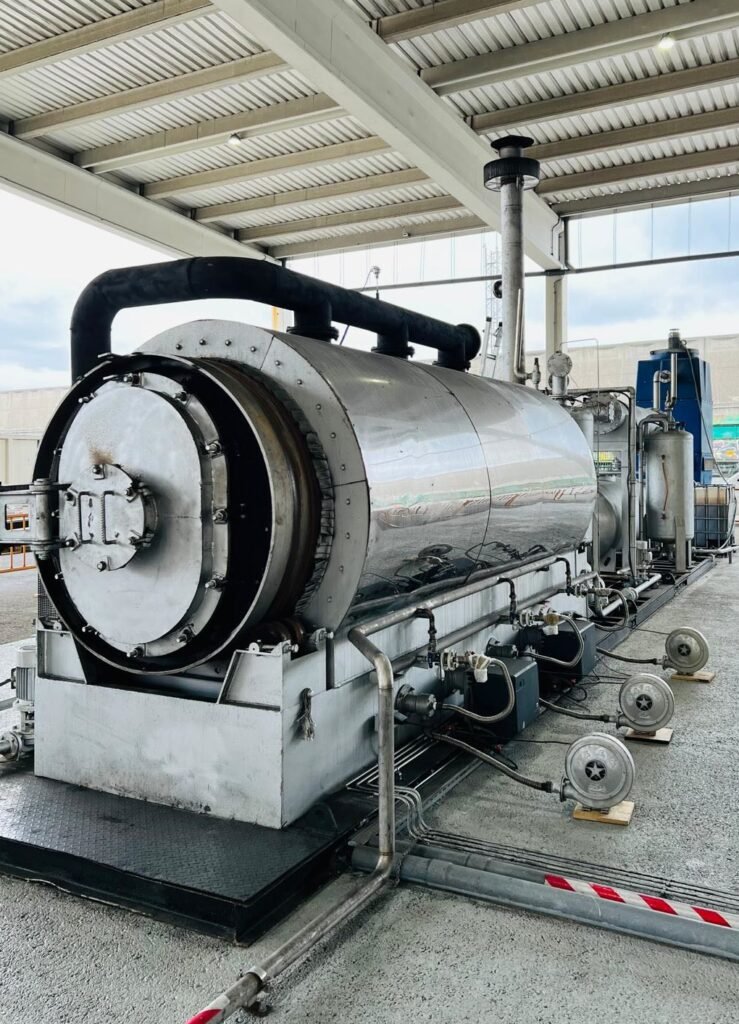
- Technology validated since 2022 at its industrial plant in the Port of Bilbao, with plastics from different sources.
- Thermal pyrolysis without catalysts, with proprietary reactive agents, which accepts mixed plastic without prior sorting by type.
- Guaranteed purchase of 100 % of the product with long-term contracts, which provides an outlet for the certified material.
For the client, this means not having to set up a certification department or look for buyers: traceability and sales are part of the same contract. It is the practical difference between chemical recycling as a concept and as a recurring business.
To understand how recycled content is attributed and what the EU has set out, read mass balance in chemical recycling.
Frequently asked questions about ISCC PLUS and environmental credits
Is ISCC PLUS mandatory?
No. It is a voluntary scheme. But many buyers of circular feedstock require it, so in practice it determines access to those markets.
How long does an ISCC PLUS certificate last?
Twelve months. It is issued per site and an annual audit must be passed to renew it.
Does mass balance mean the product contains recycled molecules?
Not necessarily. It is an audited accounting method: it guarantees that the quantity sold as circular does not exceed the quantity of circular waste that entered the system.
What is the difference between ISCC PLUS and ISCC EU?
ISCC PLUS is voluntary and is used mainly for materials and chemicals. ISCC EU verifies compliance with the Renewable Energy Directive and is the one that applies to fuels within that regulatory framework.
Can I sell plastic credits if the oil is used as fuel?
Under Verra’s methodology, no: it excludes projects whose product is used as fuel or for energy recovery.
Does chemically recycled plastic pay the plastic tax in Spain?
No, if the recycled content is proven. This was confirmed by binding ruling V0931-25 of Spain’s Directorate General for Taxation.
If you want to know what environmental value your waste can capture and which scheme to certify it under, get in touch and we will study your case.